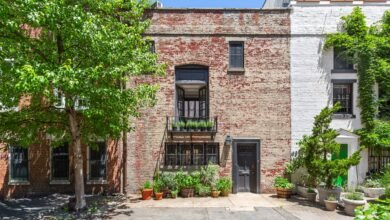
Jason B. wasn’t too worried when the Department of Finance told him the pied-à-terre tax on his Park Slope row house would be $47,504. It’s a mistake, he thought, and he would just prove it’s his full-time residence.
Even when he was confused by the exemption application, he didn’t fret. Mayor Zohran Mamdani, whom Jason had voted for, had said the tax would only hit non-New Yorkers who kept luxury crash pads in the city. Jason lived in a home his family had owned since 1976.
“I couldn’t understand the application process,” Jason said. “But I was just like, ‘I live here. I’m good. This isn’t a pied-à-terre.’”
He uploaded his driver’s license, voter registration and other proof that he lives in the house. Then, Finance asked him to submit the operating agreement for the LLC through which he owns the house.
“I thought, ‘Why the operating agreement? Who cares?’ And then I thought, “Oh, fuck.”
Jason only owns half of the LLC. The other half is owned by his brother, who lives a few blocks away. Could that be a problem?
The agency’s verdict arrived: Because Jason only owns 50 percent of the house, the nearly $50,000 annual surcharge was no mistake. He would have to pay.
In a panic, he called a few real estate lawyers, who provided conflicting opinions. One charged $1,500 and told Jason not to argue that he lives in the home. “If you do that, I guarantee you will lose,” the lawyer said. Instead, point out that a tenant lives on the ground floor.
That seemed odd. Jason thought to himself: If I left the city, used the top three floors as a pied-à-terre and kept the ground-floor tenant, I’d be spared from the tax. But not if I lived there full-time without a tenant. How does that make sense?
That wasn’t what the mayor said in his infamous “We’re taxing the rich” video. The Department of Finance’s own pied-à-terre website says at the very top, “This surcharge will only apply to [homes] that are not used as a primary residence by an owner or their immediate family members or a tenant.”
The fine print, however, says otherwise. Jason is not exempt because he only owns half of the LLC. And the family-member exemption doesn’t work because his brother is not a majority owner either.
“When an LLC owns the house, state law requires a majority interest, and DOF’s rule requires that the members who live there hold that majority,” said Michael Geylick, whose consulting firm created an online tool for surcharge appeals. “If either brother owned 51 percent, the house would have qualified.”
They also would have avoided the $47,504 surcharge had they shared ownership through a deed rather than an LLC. These details are deep within the Mamdani administration’s 26-page, 12,650-word document laying out the tax’s rules, which have flummoxed some of the city’s best real estate lawyers.
“A lot of our clients have received rejections of their exemption applications based on what we believe are overly technical or simply incorrect interpretations of the pied-à-terre tax statute,” said Timothy Noonan, a partner at Hodgson Russ. “In many cases, taxpayers like Jason, who most definitely are New York City residents and who are paying New York City personal income taxes, are being denied exemptions for one reason or another.”
The law was not designed that way, said Noonan. “It’s frustrating to see the city take this approach,” he said.
A Department of Finance spokesperson said the agency is following the state law.
“The statute governing the surcharge allows property owners, under certain circumstances, to demonstrate that they are not subject to the surcharge because their property is used as primary residence,” he noted.
Under certain circumstances?
A primary residence is a primary residence, full stop. Deed or LLC ownership shouldn’t matter. Nor should partial ownership, or renovations requiring relocation.
Gov. Kathy Hochul, who supports the tax but has criticized the city’s implementation of it, has said that to avoid the surcharge, ex-New Yorkers can move back to the city and pay city income taxes.
Jason B. never left, never stopped paying his taxes. Mamdani hit him with the surcharge anyway.
His house should also be exempt because it’s not worth more than $5 million. Un-updated Park Slope townhouses like his sell for $3.8 million to $4.5 million, but the city inexplicably raised Jason’s market value from $4.5 million to an absurd $5.9 million last year.
A year ago, only two of the 22 one- to three-family homes on his block were above the $5 million pied-à-terre tax threshold. Today, 14 of them are, according to Geylick’s analysis. The surcharge was introduced out of the blue in mid-April — a month after the deadline to challenge market values had passed.
Coincidence? We report, you decide.
Jason’s brother eventually took a bunch of documents to a Finance office in Downtown Brooklyn to add to their case. He found an employee they knew and she started a new application — which Jason didn’t know was possible. It turns out, that was the only way to make more than one argument for an exemption. This one was granted, presumably because of Jason’s tenant.
Still, he was shaken by his experience with the system.
“It’s so arbitrary,” he said. “People are going to get caught up in this.”
Read more

No solutions in sight for co-ops’ pied-à-terre problem

Lawyers scramble to exempt misapplied pied-à-terre tax

Pied-à-terre tax rolls ahead despite battle